In Canada, the amount of child support is set by the Federal Child Support Guidelines. This guide explains how the Guidelines calculate support and how to model each step in the Divorcepath child support calculator.
It covers:
- how the Guidelines and the child support tables work, including the tables that took effect on October 1, 2025;
- monthly table support (section 3) when one parent has the majority of parenting time, when parenting time is shared, and when it is split;
- special or extraordinary expenses (section 7);
- how to determine each parent's Guideline income, including imputing and grossing up income;
- the exceptions for undue hardship, high incomes and low incomes; and
- how child support interacts with income tax and spousal support.
This guide assumes support is payable. For who has to pay and who can claim support, read Entitlement to Child Support. For applying for, enforcing and changing child support, read Child Support in Canada. If you just want to run a calculation, start with the Child Support Quickstart.
This guide provides general legal information, not legal advice. If you need advice about your situation, please contact us for a referral to a family lawyer.
The Federal Child Support Guidelines
Every province and territory except Quebec uses the federal child support tables, either directly or through provincial guidelines that follow the federal ones closely. Quebec has its own child support rules, which this guide does not cover.
The Guidelines start from a presumption in section 3(1):
Unless otherwise provided under these Guidelines, the amount of a child support order for children under the age of majority is (a) the amount set out in the applicable table, according to the number of children under the age of majority to whom the order relates and the income of the spouse against whom the order is sought; and (b) the amount, if any, determined under section 7.
In other words, child support is normally the table amount (basic monthly support, often called "section 3 support") plus a share of any special or extraordinary expenses ("section 7 support"). The rest of the Guidelines deal with how to determine income and when a different amount applies: shared or split parenting time, adult children, incomes over $150,000, and undue hardship.
Because the Guidelines make support formula-driven, most disputes are about the inputs, especially each parent's income. Parents can recalculate support as incomes change, which is why regular financial disclosure matters (see Guideline income below).
The 2025 child support tables
New federal tables came into force on October 1, 2025. According to Justice Canada:
- support owed for the period from November 22, 2017 to September 30, 2025 is calculated with the 2017 tables, and support owed from October 1, 2025 onward with the 2025 tables;
- the 2025 tables do not automatically change an order made before October 1, 2025, but a different table amount can be a "change in circumstances" that supports a variation.
The Divorcepath calculator applies the table that matches the calculation's tax year and dates.
Basic monthly child support (section 3)
Basic child support comes from the table for the province or territory where the paying parent habitually resides (there are special rules if that parent lives outside Canada). Each table sets out a monthly amount based on the paying parent's annual income and the number of children.
The tables are published as income ranges of $1,000. Each row gives a basic amount, plus a percentage of the income above the bottom of the range. Here is an excerpt from the 2025 Ontario table:
| Annual income | 1 child | 2 children | 3 children | 4 children |
|---|---|---|---|---|
| $50,000 – $50,999 | $450 + 1.26% | $744 + 1.34% | $1,003 + 1.56% | $1,216 + 1.90% |
| $51,000 – $51,999 | $463 + 1.24% | $757 + 1.76% | $1,019 + 1.64% | $1,235 + 2.00% |
| $52,000 – $52,999 | $475 + 1.28% | $775 + 1.80% | $1,035 + 1.68% | $1,255 + 2.08% |
| $53,000 – $53,999 | $488 + 1.12% | $793 + 1.74% | $1,052 + 1.70% | $1,276 + 2.04% |
| $54,000 – $54,999 | $499 + 0.88% | $810 + 1.66% | $1,069 + 1.60% | $1,296 + 1.96% |
The percentage applies to income above the bottom of the range. For example, an Ontario parent earning $52,500 who pays support for two children pays $775 + 1.80% × $500 = $784 per month.
A few rules apply at the edges of the tables:
- Six or more children. The last column of each table is "six or more", so a family with more than six children uses that column.
- Low incomes. Under the 2025 tables, the table amount is $0 for incomes of $16,000 or less. Above that the amount phases in gradually (in Ontario, for one child, 9.5% of income over $16,000 up to $17,000).
- Incomes over $150,000. The last row of each table is a formula. In Ontario, for one child, it is $1,327 plus 0.76% of income over $150,000, so a parent earning $200,000 would pay $1,707 per month. A court can set a different amount on the income above $150,000 (see Incomes over $150,000).
The calculator does the table lookup for you. The key inputs are:
- each parent's province or territory of residence, which selects the table;
- each parent's income, which selects the row (see Guideline income);
- the number of children, which selects the column; and
- the parenting arrangement for each child, which decides whether the majority, shared or split rules apply.
Majority of parenting time
When a child lives with one parent for more than 60% of the time over a year (the Guidelines call this the "majority of parenting time"), the other parent pays the table amount based on their own income. The receiving parent's income does not affect the table amount, although it does affect how section 7 expenses are shared.
Shared parenting time (section 9)
When each parent has at least 40% of parenting time with a child over the course of a year, section 9 applies:
If each spouse exercises not less than 40% of parenting time with a child over the course of a year, the amount of the child support order must be determined by taking into account (a) the amounts set out in the applicable tables for each of the spouses; (b) the increased costs of shared parenting time arrangements; and (c) the conditions, means, needs and other circumstances of each spouse and of any child for whom support is sought.
The usual starting point is a set-off: each parent's table amount is calculated, and the parent with the higher amount pays the difference. In Contino v. Leonelli-Contino, 2005 SCC 63, the Supreme Court of Canada held that the set-off is a starting point, not a presumption. The court must also weigh the increased costs of shared parenting and each household's circumstances, with the aim of a fair result. This means the set-off amount is often adjusted.
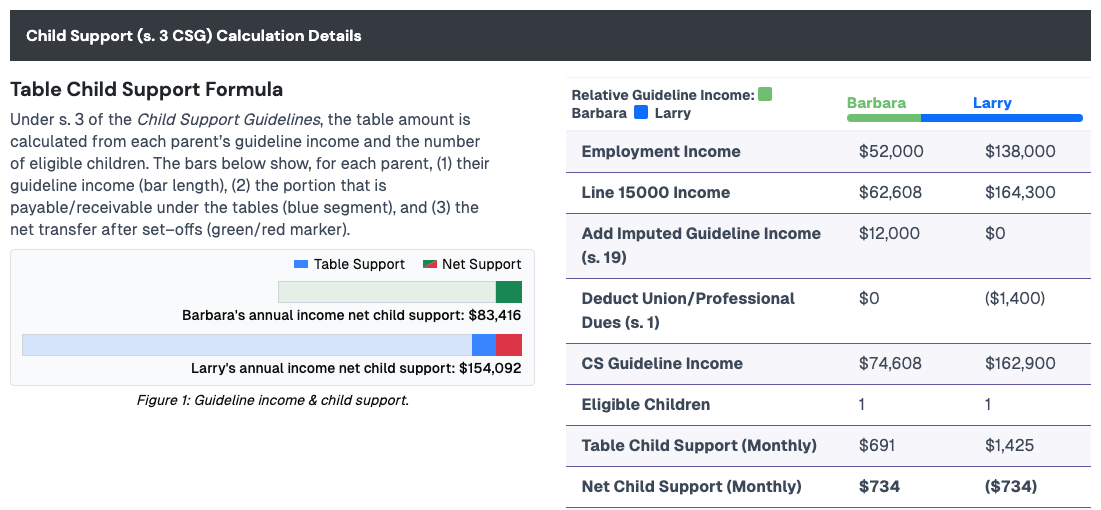
In the calculator, set the child's Parenting to Shared. The results show each parent's table amount and the net payment:
Split parenting time (section 8)
When there are two or more children and each parent has the majority of parenting time with at least one of them, section 8 applies:
If there are two or more children, and each spouse has the majority of parenting time with one or more of those children, the amount of a child support order is the difference between the amount that each spouse would otherwise pay if a child support order were sought against each of the spouses.
Each parent's table amount is calculated for the children living with the other parent, and the parent with the higher amount pays the difference. Set each child's Parenting to the parent they live with, and the calculator applies the split rule.
Special or extraordinary expenses (section 7)
Table support covers a child's ordinary costs. Section 7 allows a court to add an amount for certain additional expenses, taking into account whether the expense is necessary in light of the child's best interests and reasonable in light of the parents' and child's means and the family's spending before separation. The expense categories in section 7(1) are:
(a) child care expenses incurred as a result of the employment, illness, disability or education or training for employment of the spouse who has the majority of parenting time;
(b) that portion of the medical and dental insurance premiums attributable to the child;
(c) health-related expenses that exceed insurance reimbursement by at least $100 annually, including orthodontic treatment, professional counselling provided by a psychologist, social worker, psychiatrist or any other person, physiotherapy, occupational therapy, speech therapy and prescription drugs, hearing aids, glasses and contact lenses;
(d) extraordinary expenses for primary or secondary school education or for any other educational programs that meet the child's particular needs;
(e) expenses for post-secondary education; and
(f) extraordinary expenses for extracurricular activities.
For school expenses under (d) and extracurricular activities under (f), the expense must be "extraordinary". Section 7(1.1) defines this as an expense the requesting parent can't reasonably cover from their own income plus the table support they receive. Where that test doesn't fit, the court looks at factors such as the size of the expense relative to that income, the number of programs and activities, the child's special needs and talents, and the overall cost.
How section 7 expenses are shared
The guiding principle in section 7(2) is that the expense is shared by the parents in proportion to their incomes, after deducting any contribution from the child. Under section 7(3), the expense is first reduced by any subsidies, benefits, or income tax deductions or credits relating to it. Child care is a good example: the child care expense deduction and related tax credits can substantially reduce the net cost.
The income used to share section 7 expenses is slightly different from the income used for the table amount. Spousal support paid to the other parent is deducted from the payor's income, while the recipient keeps that spousal support in their income.
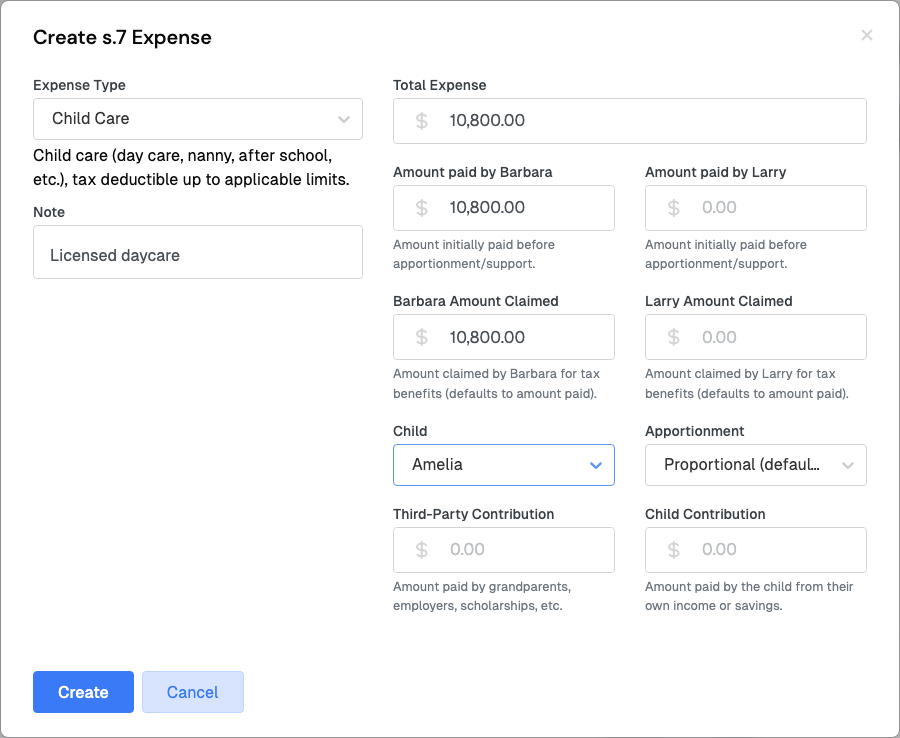
In the calculator, add each expense under S. 7 Expenses with New s. 7 Expense. Enter the total cost, the amount each parent paid and claimed for tax purposes, the child, and how the expense should be apportioned:
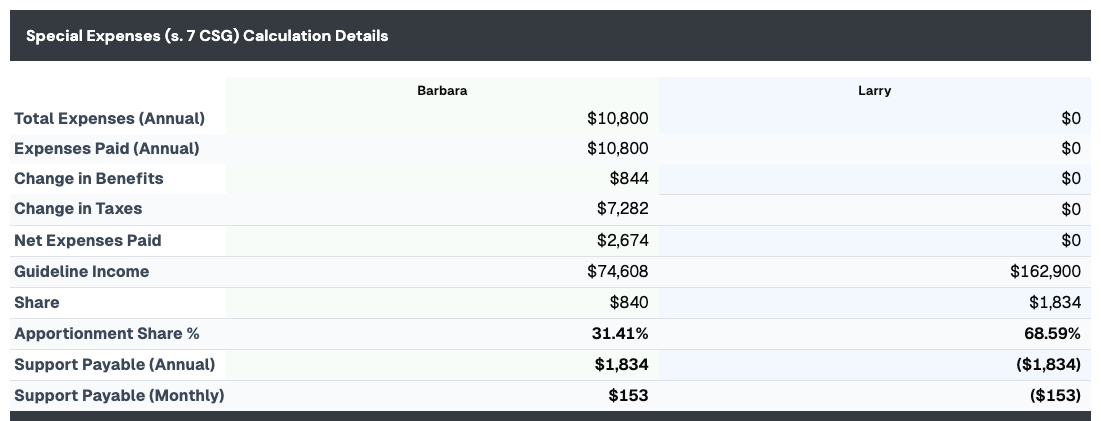
The calculator works out each parent's tax and benefit changes from the expense, then shares the net cost in proportion to Guideline income:
Guideline income
Both the table amount and the sharing of section 7 expenses depend on each parent's income as determined under the Guidelines ("Guideline income"). In primary parenting cases only the paying parent's income matters for the table amount. In shared and split cases, and for section 7 expenses, both parents' incomes matter.
Determining income can be simple for a salaried employee and much harder for a parent who is self-employed, owns a corporation, has irregular income or isn't working to capacity. Guideline income is often the most contested issue in a child support case, and you may need a family lawyer's help to get it right.
Financial disclosure
Section 21 of the Guidelines requires a parent whose income is relevant to provide, among other things:
- every personal income tax return for the three most recent tax years;
- every notice of assessment and reassessment for those years;
- for employees, the most recent statement of earnings showing year-to-date earnings (or a letter from the employer);
- for self-employed parents, partners and parents who control a corporation, business or corporate financial statements and details of payments to people they don't deal with at arm's length, for the three most recent years; and
- the most recent statement of any EI, social assistance, pension, workers' compensation, disability or other income.
A parent responding to a claim generally has 30 days after being served to provide disclosure (60 days if they live outside Canada and the United States). After an order is made, either parent can request updated income information once a year under section 25.
Keeping disclosure current protects both parents. A payor who doesn't disclose an increase in income can face a claim for retroactive support, and a recipient who doesn't ask may receive less than they are entitled to.
Determining Guideline income
Under section 16, Guideline income starts with the income sources listed under "Total income" on the T1 income tax return (line 15000), adjusted according to Schedule III. Common Schedule III adjustments include:
- deducting employment expenses that are deductible for tax purposes, such as union and professional dues;
- for the table amount, deducting spousal support received from the other parent;
- replacing the taxable (grossed-up) amount of dividends from Canadian corporations with the actual amount received;
- replacing taxable capital gains with the actual capital gains, net of actual capital losses;
- deducting business investment losses and deductible carrying charges and interest expenses;
- adding back salaries or fees paid by a self-employed parent to people they don't deal with at arm's length, unless they were necessary and reasonable; and
- adding back capital cost allowance claimed on real property.
Deductions that come after line 15000 on the tax return are not Guideline deductions unless Schedule III says so. For example, there is no Schedule III adjustment for RRSP contributions, the child care expense deduction or enhanced CPP/QPP contributions, so none of these reduce Guideline income.
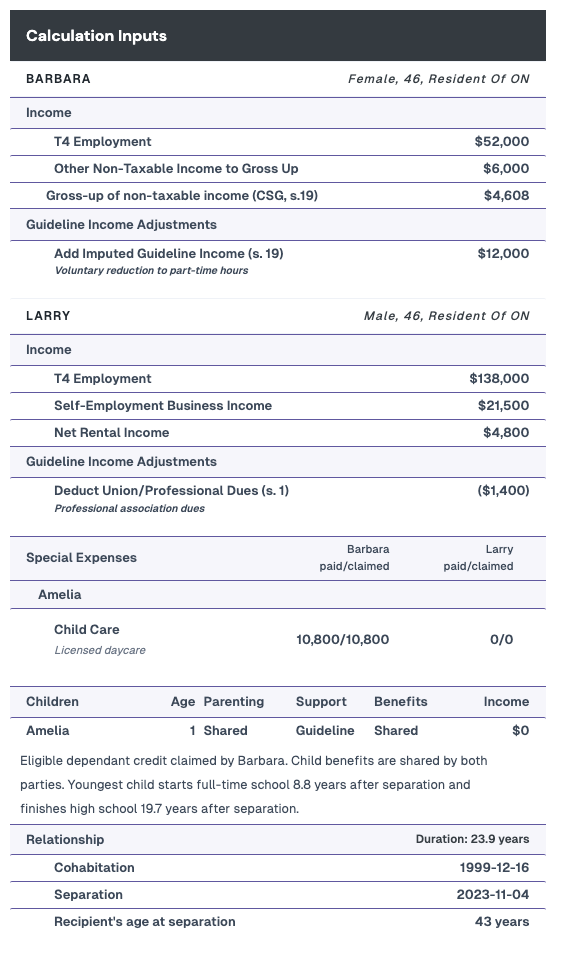
In the calculator, enter each type of income separately under Income, and add Schedule III and other adjustments under Guideline Income Adjustments. The calculator applies the standard adjustments for each income type automatically (for example, it uses the actual amount of dividends rather than the taxable amount). Use adjustments for anything that depends on the facts, such as dues, business losses or imputed income. The adjustments appear in the calculation inputs and in every report:
Imputing income
Sometimes a parent's actual income doesn't reflect what they could or should be earning. Section 19(1) lets a court "impute" (add) income in circumstances that include where:
- the parent is intentionally under-employed or unemployed, unless that is required by the needs of a child or by the parent's reasonable educational or health needs;
- the parent is exempt from income tax, lives in a country with significantly lower tax rates, or earns a significant portion of income from sources taxed at lower rates (see Grossing up income);
- income has been diverted, or the parent's property is not reasonably used to generate income;
- the parent has failed to provide income information when legally required to;
- the parent unreasonably deducts expenses from income; or
- the parent is a beneficiary of a trust.
The party seeking to impute income has to establish the basis for it. In Drygala v. Pauli (2002), 61 O.R. (3d) 711, the Ontario Court of Appeal held that a parent doesn't need to intend to avoid support for income to be imputed for intentional under-employment. In Hanson v. Hanson, [1999] B.C.J. No. 2532 (S.C.), at para. 14, the court summarized the principles courts apply:
1. There is a duty to seek employment in a case where a parent is healthy and there is no reason why the parent cannot work. It is "no answer for a person liable to support a child to say he is unemployed and does not intend to seek work or that his potential to earn income is an irrelevant factor."
2. When imputing income on the basis of intentional under-employment, a court must consider what is reasonable under the circumstances. The age, education, experience, skills and health of the parent are factors to be considered in addition to such matters as availability of work, freedom to relocate and other obligations.
3. A parent's limited work experience and job skills do not justify a failure to pursue employment that does not require significant skills, or employment in which the necessary skills can be learned on the job. While this may mean that job availability will be at the lower end of the wage scale, courts have never sanctioned the refusal of a parent to take reasonable steps to support his or her children simply because the parent cannot obtain interesting or highly paid employment.
4. Persistence in unremunerative employment may entitle the court to impute income.
5. A parent cannot be excused from his or her child support obligations in furtherance of unrealistic or unproductive career aspirations.
6. As a general rule, a parent cannot avoid child support obligations by a self-induced reduction of income.
There are two ways to enter imputed income in the calculator:
- As income, for example as additional employment income. Taxes, benefits and net disposable income are then calculated as though the parent actually earned it.
- As a Guideline income adjustment, such as Add Imputed Guideline Income (s. 19). The amount is used to calculate support, but taxes and benefits are based on the parent's actual income.
For table support alone, both methods give the same result. For section 7 expenses and spousal support, which depend on taxes and net income, the method can change the result by hundreds or thousands of dollars. If you're unsure which to use, contact us and we'll help you set up the calculation.
Grossing up income
The table amounts assume income is taxed at ordinary rates. When a parent pays little or no tax on their income, sections 19(1)(b), (c) and (h) allow the court to impute additional income where:
(b) the spouse is exempt from paying federal or provincial income tax;
(c) the spouse lives in a country that has effective rates of income tax that are significantly lower than those in Canada;
…
(h) the spouse derives a significant portion of income from dividends, capital gains or other sources that are taxed at a lower rate than employment or business income or that are exempt from tax
"Grossing up" means working out how much pre-tax employment income the parent would need to earn to take home the same after-tax amount they actually receive. The difference between that grossed-up amount and their actual income is added to their Guideline income.
The calculator does the math. Enter the non-taxable amount with the income type Other Non-Taxable Income to Gross Up. The calculator adds an automatic Gross-up of non-taxable income (CSG, s.19) line, shown in the calculation inputs above, and uses the total as Guideline income. Where tax-preferred income such as dividends or capital gains makes up a significant portion of a parent's income, the calculator can also add the tax savings to Guideline income.
Gross-up questions can be legally complex. If in doubt, consult a family lawyer.
Exceptions to the table amount
Undue hardship (section 10)
Section 10 allows a court to order a different amount (usually less) if the parent making the request, or a child, would otherwise suffer undue hardship. Paying support being difficult isn't enough. The hardship must be exceptional, excessive or disproportionate. Section 10(2) lists circumstances that may cause undue hardship:
(a) the spouse has responsibility for an unusually high level of debts reasonably incurred to support the spouses and their children prior to the separation or to earn a living;
(b) the spouse has unusually high expenses in relation to exercising parenting time with a child;
(c) the spouse has a legal duty under a judgment, order or written separation agreement to support any person;
(d) the spouse has a legal duty to support a child, other than a child of the marriage, who is (i) under the age of majority, or (ii) the age of majority or over but is unable, by reason of illness, disability or other cause, to obtain the necessaries of life; and
(e) the spouse has a legal duty to support any person who is unable to obtain the necessaries of life due to an illness or disability.
The list is not exhaustive. But even where hardship is established, section 10(3) requires the court to deny the claim if the household of the parent claiming hardship would have a higher standard of living than the other parent's household after support is paid. Schedule II of the Guidelines sets out a test for comparing household standards of living, which divides each household's income by Statistics Canada's low-income measure for a household of that size.
In the calculator, open Show More Options, choose the Undue Hardship tab, and add each hardship factor with New u.h. factor:
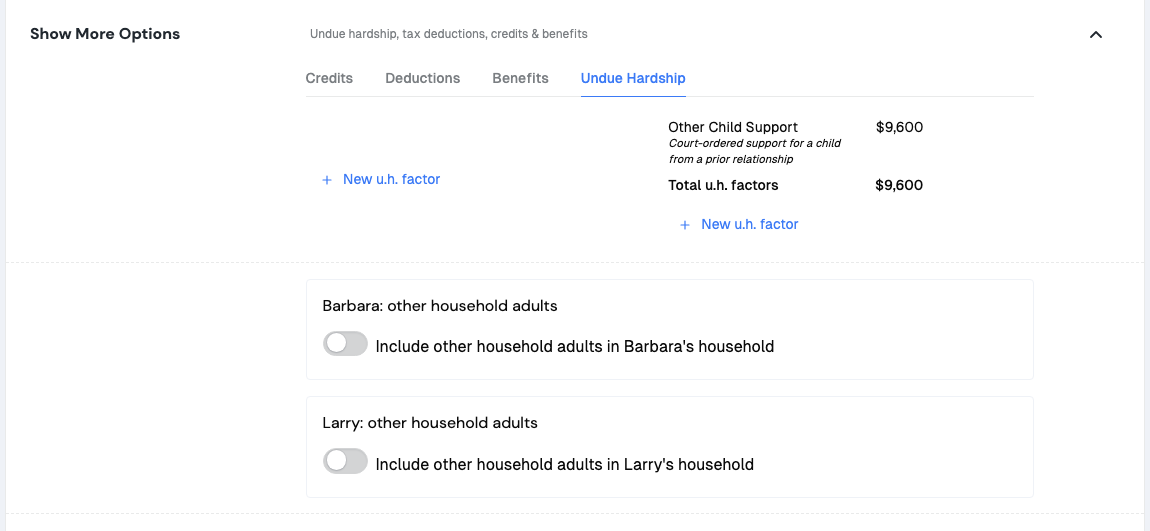
To include the household standard-of-living comparison in the condensed report, set Display undue hardship analysis in report? to Yes on the Settings tab. You can include other adults in each household on the same Undue Hardship tab.
Incomes over $150,000 (section 4)
The tables apply a formula to income above $150,000. Section 4 allows a court to depart from that formula if it considers the table amount inappropriate:
Where the income of the spouse against whom a child support order is sought is over $150,000, the amount of a child support order is (a) the amount determined under section 3; or (b) if the court considers that amount to be inappropriate, (i) in respect of the first $150,000 of the spouse's income, the amount set out in the applicable table for the number of children under the age of majority to whom the order relates; (ii) in respect of the balance of the spouse's income, the amount that the court considers appropriate, having regard to the condition, means, needs and other circumstances of the children who are entitled to support and the financial ability of each spouse to contribute to the support of the children; and (iii) the amount, if any, determined under section 7.
Courts start from the table amount, and the parent seeking a different amount must show that it is inappropriate. Courts consider the children's actual needs and circumstances, the standard of living in each household before and after separation, and whether the table amount would go beyond supporting the children. In most cases, the table amount is ordered.
When a paying parent's Guideline income is over $150,000, the calculator flags it in the Exceptions, Ceilings & Floors section of the condensed report, and in the detailed report:

Low incomes
Under the 2025 tables, no table support is payable on income of $16,000 or less, and the amounts above that phase in gradually. Before concluding that a low-income parent pays nothing, consider whether income should be imputed (for example, for intentional under-employment) or grossed up. Non-taxable income such as some disability benefits can bring a parent above the threshold once it is grossed up. Even when the amount is small, it often makes sense to have a support order in place so that it can be varied if circumstances change.
Children over the age of majority
For a child who is the age of majority or over, section 3(2) allows the court to use the table amount, or a different amount if the table approach is inappropriate, having regard to the child's needs, means and circumstances and each parent's ability to contribute. Entitlement to Child Support explains when adult children qualify for support and how courts approach the amount.
Child support and income tax
Child support paid under a court order or written agreement made after April 1997 is not deductible by the paying parent and not taxable to the recipient. (Some older orders and agreements made before May 1997 are still taxed under the old rules unless they were varied or the parents elected otherwise.) The table amounts already account for this.
A few related tax rules affect support calculations. For details, see the CRA's Income Tax Folio on support payments.
- Legal fees. A recipient can deduct legal and accounting fees to establish child support, seek an increase, defend against a reduction, or collect late payments. A paying parent can't deduct fees to establish, contest, reduce or end support, and neither parent can deduct fees for the divorce itself or for parenting arrangements.
- Eligible dependant amount. A parent who pays child support for a child generally can't claim the amount for an eligible dependant for that child. In shared parenting arrangements where an order or written agreement clearly requires both parents to pay support, one of them may claim it if they agree who will. The CRA's position is that an order that simply sets off the two table amounts doesn't by itself require both parents to pay.
- Canada Child Benefit. When a child lives with each parent at least 40% of the time, each parent receives 50% of the benefit they would get with full-time custody, based on their own family income.
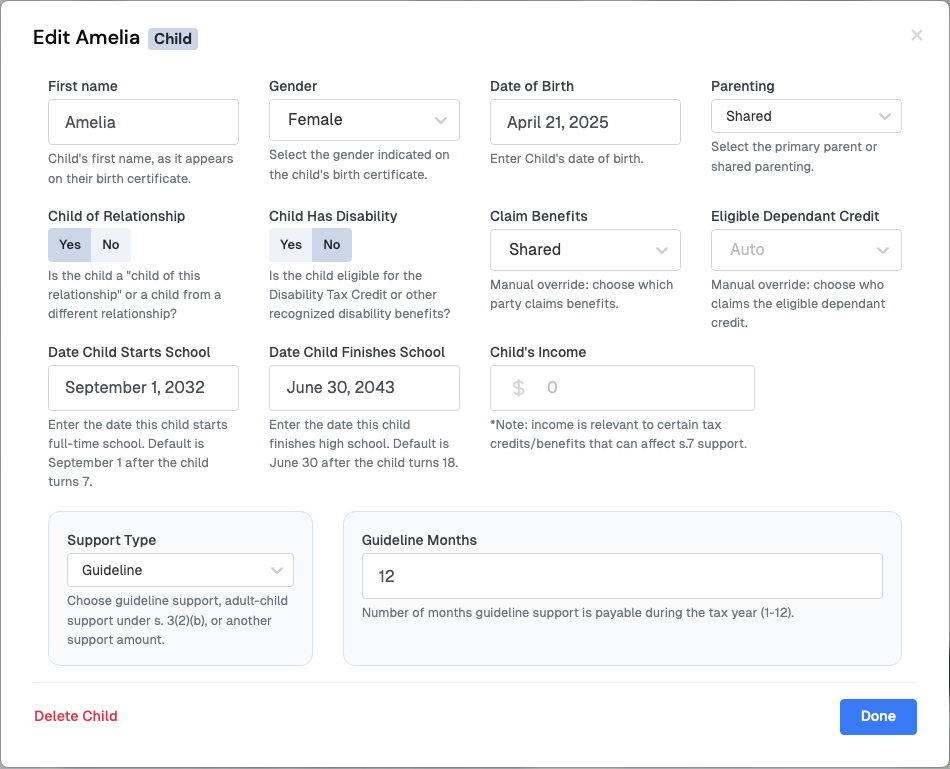
The calculator estimates each parent's taxes, credits and benefits. By default, benefits follow each child's parenting arrangement, and the eligible dependant credit goes to the parent the child lives with (in shared parenting, the parent with the lower Guideline income). You can change these for each child with Claim Benefits and Eligible Dependant Credit. Any changes are noted in the reports.
Child support and spousal support
Child support comes first. Under section 15.3 of the Divorce Act, a court considering both child support and spousal support "shall give priority to child support". If that leaves less room for spousal support, the court must record its reasons. Spousal support is calculated after child support, and the Spousal Support Advisory Guidelines use different formulas depending on whether child support is also being paid.
Spousal support also affects Guideline income. For the table amount, spousal support received from the other parent is deducted from the recipient's income. For sharing section 7 expenses, spousal support paid to the other parent is deducted from the payor's income.
To calculate child and spousal support together, start a Spousal & Child Support calculation. Read How to Calculate Spousal Support for more.
Calculating child support online
The Divorcepath child support calculator applies the Federal Child Support Guidelines for every province and territory except Quebec. It handles table support, shared and split parenting time, section 7 expenses, Guideline income adjustments, gross-ups and undue hardship. It produces condensed and detailed reports you can share or file.
To get started, read the Child Support Quickstart or take the interactive tour above. If you have questions about the calculator, you can reach us by chat or email. We can help you use the calculator and provide general legal information, but we'll refer you to a family lawyer if you need legal advice.
